MAJORITY: Mobile banking
MAJORITY USA, LLCFinanceVerified
- 12.00K Reviews
- 4.7
- Downloads
- 1,000,000+
- Price
- Free
Screenshots
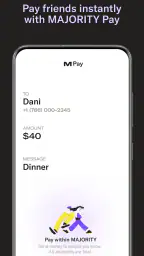
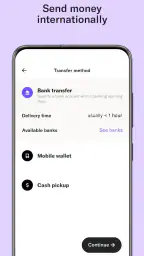
 Analysis by Appwesome
MAJORITY: Mobile banking is the kind of finance app that makes a strong first impression because it focuses on a very specific everyday problem: giving people a US account and debit card without requiring an SSN. I found that focus more useful than a crowded banking app that tries to become an investment platform, budgeting suite, and rewards center all at once. Its main promise is practical access to money, sending funds home, credit-building support, and staying connected in one place.
After spending time with it, my opinion is that the app earns its place most easily for newcomers to the US, international workers, and anyone who needs a straightforward way to manage routine spending without beginning with a traditional bank relationship. It is free, rated for Everyone, and developed by MAJORITY USA, LLC. The important question is not whether it feels convenient during the first few days, but whether its account and debit-card workflow remains useful once the novelty disappears.
Why the first week feels so practical
The strongest part of the opening experience is the clear purpose. I do not have to guess whether this is mainly a stock-trading tool, a coupon app, or a complicated personal-finance dashboard. It is built around a US account, a debit card, transfers, and financial routines that matter when someone is establishing a life in the country. That narrow identity makes it easier to understand than many general-purpose banking alternatives.
The no-SSN positioning is especially important for people who may struggle to access conventional financial services at the beginning of their US journey. I would not treat that phrase as a reason to skip every normal verification step, though. A financial app still needs to establish identity and eligibility in its own process, so I would prepare the personal information requested during registration rather than expecting an instant, completely frictionless account.
During the first week, the debit card is likely to become the center of the experience. A card connected to a dedicated account can make ordinary purchases easier to organize than relying on cash or repeatedly moving money through another person’s account. I like that this gives a new user a clearer boundary between money intended for daily expenses and money held elsewhere.
The app also makes sense for someone who regularly sends money home. That use case changes the value calculation: the service is not only about paying for groceries or transport in the US, but also about maintaining a financial connection with family abroad. I would still compare the final transfer experience and cost with specialist remittance services before making it my only option. Convenience is valuable, but frequent senders should always pay attention to the amount received, the speed, and the exchange-rate result.
One useful first-week habit is to treat the account as a routing point rather than immediately moving every financial activity into it. I would begin with a manageable amount, use the debit card for a few predictable purchases, and test a small transfer before depending on the service for rent or an urgent family payment. That approach reveals how well the workflow fits my routine without creating unnecessary disruption.
Other Stories to Read




The credit-building angle also deserves careful interpretation. It can be attractive to someone trying to establish a stronger financial profile, but credit improvement is not an instant result and should not be confused with simply having a debit card. I would read the in-app explanations closely, understand what actions are expected, and keep the account funded enough for the intended routine. The benefit is most meaningful when it supports disciplined behavior over time.
A realistic everyday routine
Imagine a worker receiving regular income elsewhere, moving a planned spending amount into the account, and using the debit card for food, phone service, and local transportation. At the end of the week, that person can review what remains, reserve the next transfer for family, and avoid mixing those expenses with cash kept for bills. The app becomes useful not because it performs a dramatic financial transformation, but because it gives a repeatable structure to several small tasks.
For that routine, I would set a personal rule: keep only the amount needed for near-term spending in the account and review transfers before confirming them. This is not a criticism of MAJORITY; it is sensible behavior for any mobile financial service. A simple workflow becomes safer when I separate everyday spending, family support, and longer-term savings instead of treating one balance as a complete financial plan.
The first-week appeal is therefore strongest when the user has a clear reason for joining. If I only want a conventional checking account with a broad branch network, the app may feel more specialized than necessary. If I need an accessible entry point, a debit card, and a way to manage cross-border responsibilities, its focused design is much easier to appreciate.
What remains valuable month after month
Recurring value comes from repetition. A finance app stays installed when it reduces a task I perform every week or every month, not when its onboarding feels polished once. In MAJORITY’s case, that recurring value can come from using the account for regular spending, sending money home, and following a consistent credit-building routine.
I think the account is most useful as a financial “home base” for people whose needs are connected to relocation or family abroad. A traditional bank may handle domestic banking well, while a separate remittance service may handle international payments well. MAJORITY attempts to bring those needs closer together. That can save mental effort, especially for someone who does not want to maintain several unfamiliar services.
There is a trade-off, however. A single app is convenient only when it performs well enough across all the jobs I give it. A specialist transfer service might be preferable for someone who compares exchange rates constantly or sends large amounts on a strict schedule. A full-service bank may be better for customers who need a wider range of account types, lending products, or in-person support. MAJORITY’s lasting usefulness depends on whether its combination is more valuable to me than the best individual alternative.
The app’s credit-building purpose can also create a monthly discipline loop. I would not open it merely to watch a score change. I would use it alongside sensible habits: keeping spending predictable, avoiding money movements I cannot cover, and checking the account before scheduled obligations. The app may support that effort, but it cannot replace the behavior that makes credit-building meaningful.
One non-obvious advantage of a focused financial app is reduced decision fatigue. When I open an app with a dozen unrelated features, I can spend more time navigating than acting. A service centered on an account, card, transfers, and related support can be easier to revisit. That matters for users who are not enthusiastic about personal finance and need a tool they will actually open.
Another useful workflow is to use the app as a checkpoint before sending money home. I would confirm the recipient details, the amount intended for the family, and the amount left for local expenses before completing the transfer. This simple pause helps prevent the common mistake of treating a successful transfer as the end of the task when the sender still has bills to cover.
MAJORITY has a 4.7 average from around 23 thousand ratings, and it has passed one million installs. Those figures suggest that the service has attracted substantial attention and that many users find the core idea worthwhile. I still would not use popularity as a substitute for checking whether the account fits my own transfer habits, card needs, and tolerance for managing money primarily through a phone.
Who gets the most lasting value
I would recommend it first to people arriving in the US who need a practical account and debit card, workers supporting relatives in another country, and users who want to explore a structured path toward building credit. It may also suit someone who prefers handling banking tasks digitally and values having related services gathered under one account.
I would be more cautious for a person who already has a bank that handles direct deposits, domestic payments, and international transfers comfortably. In that situation, adding another financial app can create extra balances to monitor rather than real savings of time. I would also look elsewhere if branch access, complex account products, or highly specialized international transfer comparisons are central requirements.
Families should think about access and responsibility before sharing financial routines through one account. A debit card can simplify spending, but it also makes it important to know who controls the account, who checks transactions, and how money is reserved for essential expenses. I would establish those rules before treating the service as a shared household solution.
The maintenance cost and where fatigue begins
The maintenance burden is not necessarily technical; it is behavioral. Any mobile banking service asks me to keep my phone secure, review activity, remember where money is held, and respond promptly when something looks unfamiliar. MAJORITY becomes worthwhile only if I am willing to make those checks part of my routine.
I would review transactions after regular spending sessions rather than waiting for a problem to become serious. I would also keep contact and account details current, especially if I move, change phone numbers, or begin using the service in a different way. These are ordinary financial habits, but they matter more when the phone is the main doorway to the account.
Version 5.14.0 is the current version, and the app runs on operating system version 9 or later. That makes device compatibility worth checking before installation, particularly if I use an older phone. Keeping the operating system and app reasonably current is part of the maintenance routine because financial tools should not be treated like disposable apps that can remain untouched indefinitely.
The first source of fatigue is repeated verification or uncertainty around a transfer. Even when security checks are appropriate, interruptions become frustrating if I am trying to handle an urgent family payment. My practical solution would be to avoid leaving important transfers until the last minute. I would complete routine payments earlier and keep a small emergency plan outside the app.
A second source of fatigue is balance fragmentation. If I use MAJORITY for spending, another service for savings, and a third for remittances, the convenience of each individual tool can produce a confusing overall picture. I would decide in advance which account pays for which category. Without that rule, it becomes easy to underestimate spending because money is spread across several places.
A third issue is expectation management. The phrase “build credit” can make a product sound like a shortcut, while real progress requires patience and consistent financial decisions. I would judge the app by whether it helps me follow a sustainable routine, not by how quickly I expect a credit outcome. Anyone seeking immediate borrowing power should consider whether a different financial product is more appropriate.
There is also the emotional fatigue of managing family support. Sending money home can be meaningful, but it can also become unpredictable. I would use a recurring personal budget, even if the transfer itself is manual, so that generosity does not quietly consume money needed for housing, food, or transport. The app can make the movement of money easier; it cannot decide what I can responsibly afford.
How it compares with familiar alternatives
Compared with a traditional US bank, MAJORITY feels more approachable for a user whose immediate priorities are account access, debit spending, and connections abroad. A conventional bank may offer a broader ecosystem, but that breadth can come with requirements or workflows that are less comfortable for newcomers. The better choice depends on whether I value specialized accessibility or a wider banking relationship.
Compared with a prepaid card, the app appears more purposeful for someone who wants account functionality alongside debit spending and credit-building support. A prepaid option may be simpler for limited purchases, but it may not address the same relocation and family-transfer needs. I would compare the actual account terms and everyday usability rather than assuming one category is automatically superior.
Compared with a dedicated remittance app, MAJORITY’s appeal is consolidation. I can potentially manage domestic spending and sending money home from one financial environment. A specialist may still win for a user who sends money frequently and wants to compare every transfer detail. For occasional senders, the reduced number of apps may matter more than optimizing every individual transaction.
Compared with a credit card, a debit card does not encourage borrowing in the same way, which may be helpful for someone trying to control spending. On the other hand, a person specifically seeking card-based rewards or a conventional credit history strategy may need a separate product. I would see MAJORITY as a foundation for a particular financial situation, not a universal replacement for every account and card.
My long-term verdict
After the initial excitement fades, MAJORITY remains convincing when its central combination matches my life: a US account and debit card, the ability to send money home, and support for a more organized path toward credit-building. Those are recurring needs, not novelty features, for the people the app is designed to serve.
Its weaknesses are mostly about fit and discipline. I would not choose it simply because it is free, and I would not assume that a high average rating guarantees the exact transfer experience or account workflow I want. I would test it with modest amounts, compare it with my current bank and remittance options, and decide whether having one focused service genuinely reduces effort.
For a newcomer without an SSN who needs a practical financial starting point, I can see MAJORITY becoming a lasting part of the monthly routine. For an established bank customer with broad needs, it may be an unnecessary extra layer. That distinction is important: the app is strongest when it solves a specific access and connection problem, not when it is forced to imitate every kind of bank.
My final recommendation is to keep it if the debit account, family transfers, and credit-building routine all receive regular use. If I stop using two of those three areas, I would reassess whether the app still earns space on my phone. Its lasting value comes from dependable financial habits, not from downloading it once and hoping it changes everything.
MAJORITY: Mobile banking is free and available to Everyone, which lowers the barrier to trying it. I would approach it thoughtfully, start small, learn the transfer and account workflow, and then make it part of my routine only if it continues to simplify real monthly responsibilities. For the right user, that is a strong and practical reason to keep it installed.
Highlights
- Simple mobile banking tools for checking balances and managing everyday finances.
- Useful spending insights can help users understand where their money goes.
- Mobile access makes banking convenient without visiting a physical branch.
- Security features help protect account access and sensitive financial information.
- Clear transaction history makes it easier to monitor payments and deposits.
Limitations
- Some features may depend on the user’s country
- bank
- or account eligibility.
- Support response times may vary when dealing with account or payment issues.
- A stable internet connection is needed for most banking functions.
- Not all traditional banking services may be available in the app.
- Users should review fees and limits before using transfers or other paid services.
Frequently Asked Questions
01What is MAJORITY: Mobile banking, and who is it designed for?
MAJORITY is a mobile banking and financial services app focused on immigrants, international families, and people who need convenient ways to manage money across borders. Depending on eligibility and location, the app may provide services such as a spending account, debit card, money transfers, bill payments, mobile phone plans, and other member benefits. Available features can vary by country and current membership terms.
02Is MAJORITY a real bank, and is my money protected?
MAJORITY is a financial technology service rather than a traditional bank branch. Banking services and accounts may be provided through partner financial institutions, so users should review the applicable account agreement and disclosures before signing up. Protection, insurance coverage, limits, and eligibility depend on the partner institution and the user’s location. Always confirm these details inside the app or on the official website.
03What documents are required to create a MAJORITY account?
During registration, MAJORITY may ask for personal information such as your legal name, date of birth, address, phone number, and Social Security or tax identification details where required. Identity verification may also involve uploading an approved government-issued document or completing additional checks. Requirements can differ according to your country, immigration status, product selection, and applicable financial regulations.
04Can I send money internationally with MAJORITY?
MAJORITY is built with international money movement in mind, and eligible users may be able to send remittances to supported countries. Before confirming a transfer, check the recipient country, delivery method, exchange rate, transfer fee, processing time, and any transaction limits shown in the app. Availability and pricing can change, and some transfers may require additional identity or compliance verification.
05Are there fees or subscription costs when using MAJORITY?
MAJORITY may operate with a membership or subscription model, and certain services can involve separate charges. Possible costs may include monthly membership fees, out-of-network ATM fees, expedited transfer charges, exchange-rate margins, replacement card fees, or other service costs. The exact pricing depends on your plan and location, so review the current fee schedule and transaction summary before completing any payment or transfer.


